
Summary
Klaviyo Stock Not Available: Why It's Private in 2026
Klaviyo stock is not available to buy anywhere. As of September 2026, the company is still private after withdrawing its IPO filing in 2023, which means there's no ticker, no shares on any exchange, and no way for a regular investor to buy in.
This catches a lot of DTC brands off guard, because September 2023 had genuine IPO buzz and plenty of people assumed Klaviyo would list eventually. If you're trying to figure out whether this matters for platform evaluation or investment exposure, here's the full picture: why they pulled back, what the valuation looks like now, whether secondary markets are a real option, and what actually matters for brands running email on the platform.
Why Is There No Klaviyo Stock in 2026?
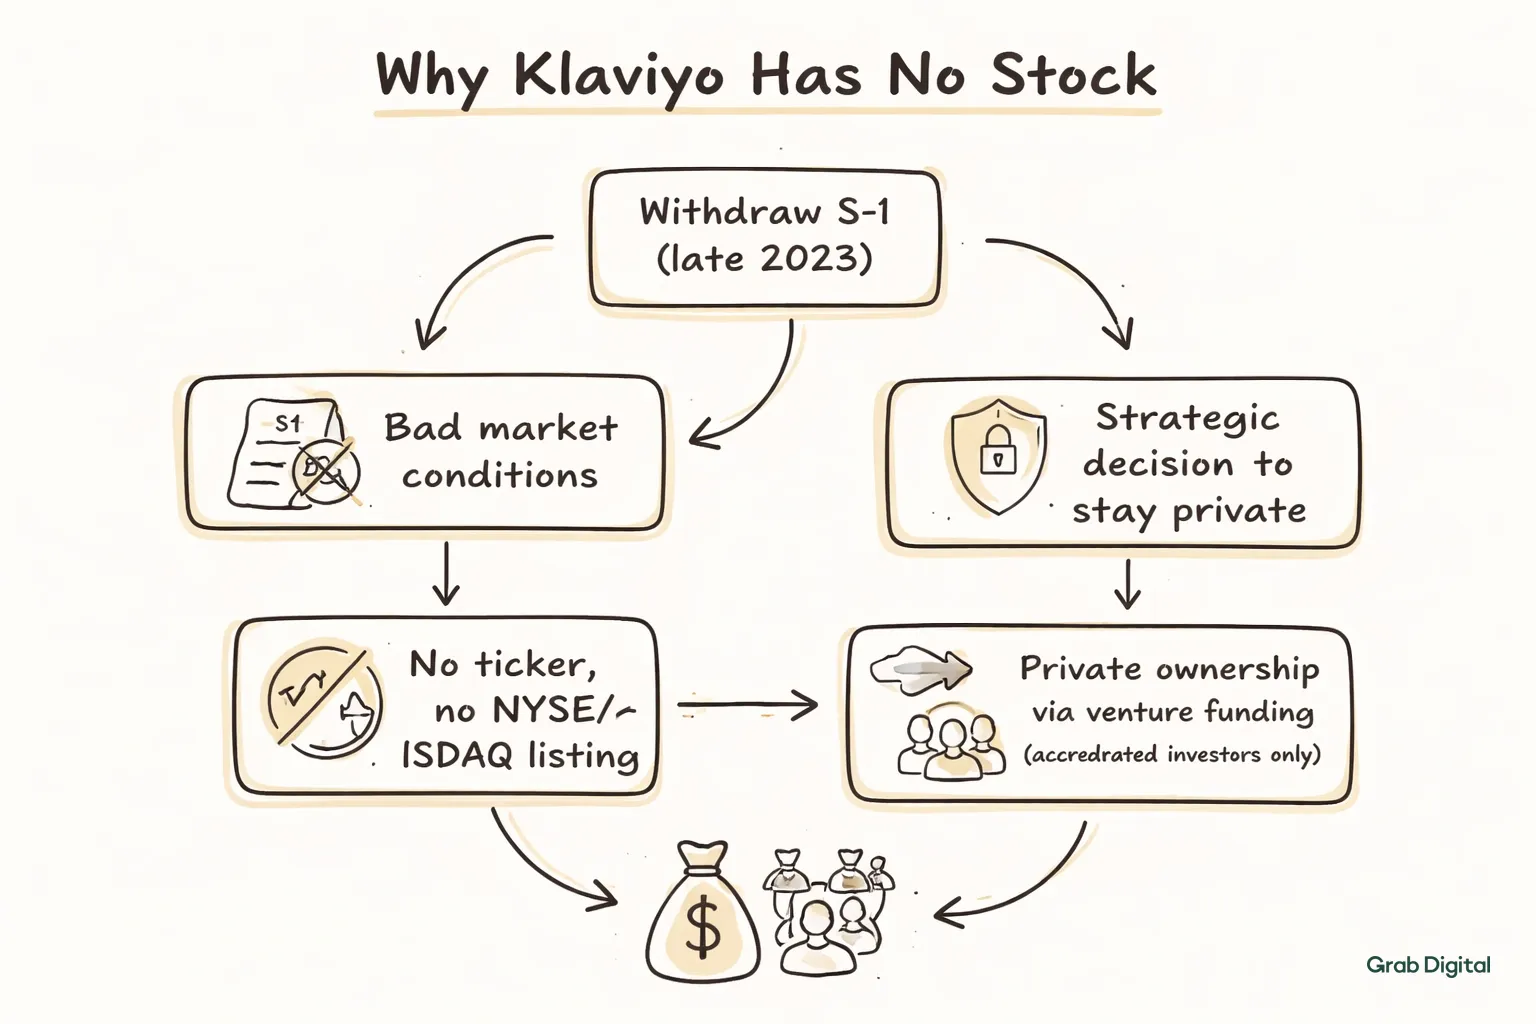
Klaviyo withdrew its S-1 filing in late 2023. The official reason was bad market conditions and strategic reasons to stay private. The translation: they didn't want to accept a crushed valuation. There is no KVYO ticker, and no listing on the NYSE or NASDAQ.
Private companies simply don't list on exchanges. You can't buy Klaviyo on Robinhood, Fidelity, or Schwab. Shareholder composition stays controlled through private funding rounds, and no open-market transactions are allowed.
That hasn't changed through September 2026. There's been no second IPO attempt. Klaviyo operates as a venture-backed private company, with ownership limited to accredited investors, institutional funds, and employees with vested options. For more on how the company's structure and roadmap tie together, our Klaviyo private company status explainer goes deeper on the specifics.
For DTC brands using Klaviyo as a platform, private status is probably good news. There's no quarterly earnings pressure forcing short-term metric chasing over customer success. If you're working with a Klaviyo agency like ours, platform continuity beats stock ticker drama every time.
What Is Klaviyo Actually Worth Right Now?
Klaviyo's last disclosed valuation was $9.5 billion, set during its 2021 Series D round. Nobody outside the company knows the current number for certain, because private valuations only update when new funding happens or secondary trades leak to the media.
Private market multiples got hit hard between 2021 and 2024. SaaS revenue multiples compressed 40 to 60 percent across the board during that stretch. Klaviyo's paper valuation almost certainly dropped from that $9.5 billion peak even without any public announcement.
Platforms like Forge Global and EquityZen occasionally facilitate private share trades for late-stage companies like this one. These deals happen between accredited investors and existing shareholders wanting liquidity. Volume is minimal, and pricing gets negotiated case by case.
There's no real secondary market for Klaviyo shares as of September 2026. Sporadic trades might happen through broker-dealer networks for high-net-worth clients, but that's not accessible to retail investors and doesn't reflect genuine market depth. Without exchange trading, price discovery stays opaque.
What Does Klaviyo's Private Status Mean for Users?
It mainly means less financial transparency, not more platform risk. Platform risk works differently for public versus private vendors. Public companies deal with regulatory scrutiny and shareholder accountability that private firms skip entirely.
Klaviyo makes product decisions without quarterly earnings calls pushing Wall Street optics over customer needs. That freedom has let them invest in CDP features, SMS expansion, and advanced segmentation without justifying burn rate to public investors. The platform has likely evolved faster without analyst expectations sitting over its shoulder.
The tradeoff is real, though: you get way less transparency. You can't pull a 10-K to check revenue growth, churn, or cash runway, so assessing long-term stability gets harder when financial health stays hidden.
For brands with real revenue flowing through email, that's worth planning around. We tell clients to diversify so no single platform controls more than 40% of attributable revenue. Even when working with a Klaviyo agency, keeping owned customer data outside Klaviyo protects your optionality if anything ever changes.
Book a free consultation to audit your email setup and find dependency risks that could hurt revenue if platform dynamics shift.
Can You Buy Klaviyo Shares on the Secondary Market?
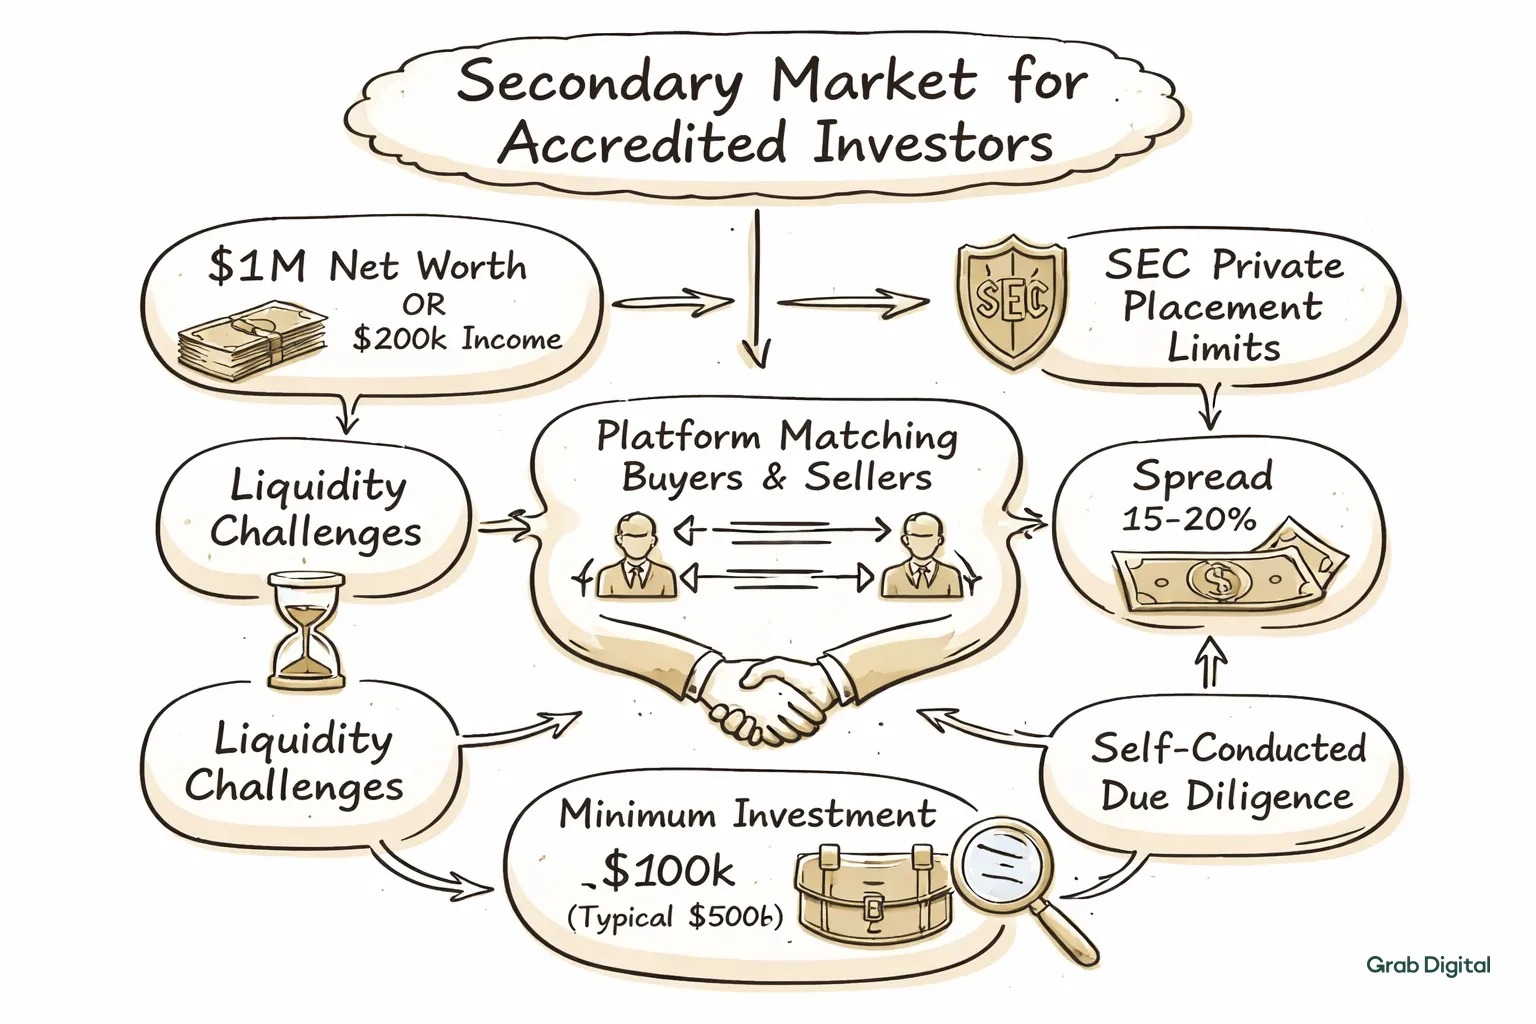
Only if you're an accredited investor, and even then, liquidity is thin. Accredited status means a $1 million net worth excluding your primary residence, or $200,000 in annual income. That's the SEC limit on who can do private placement deals for companies like Klaviyo.
Secondary platforms match qualified buyers with existing shareholders wanting liquidity through bilateral transactions with negotiated pricing. Minimums typically start around $100,000, though real positions tend to need $500,000 or more.
Liquidity is genuinely poor compared to public markets. Public stocks trade continuously. Secondary private deals depend on matching buyer interest with seller willingness, and months can pass between lots, with spreads hitting 15 to 20 percent.
Due diligence is entirely on you in these deals. There's no analyst coverage. Projections come from company materials that aren't audit-grade, and valuation gets built from multiples applied to estimates, not audited numbers.
This works for sophisticated investors with long horizons. For retail investors wanting SaaS exposure, public options like Shopify offer actual liquidity you can act on the same day.
Should DTC Brands Care About Klaviyo's Stock Status?
Not for day-to-day decisions. The ticker doesn't change deliverability, automation, or segmentation features driving revenue right now.
But ownership does shape long-term strategy. Private companies can invest in R&D without quarterly judgment. Public companies tend to monetize users faster through price hikes and margin expansion. Klaviyo staying private potentially means more predictable pricing for mid-market DTC brands over the next few years.
Acquisition risk differs too. A private Klaviyo could get acquired by Salesforce, Adobe, or HubSpot without a shareholder vote. Public companies face proxy battles and regulatory reviews before that kind of ownership shift, which gives customers a bit more warning.
If you're a brand doing $1M to $10M, these dynamics matter less than execution. Does your email automation drive 25 to 35 percent of revenue with solid attribution? Below that, ownership structure won't fix what's actually broken.
We see brands obsessing over Klaviyo's corporate structure while their core flows stay broken and campaigns fire inconsistently. That's backwards. Build infrastructure that works regardless of vendor.
What Are the Public Alternatives to Klaviyo?
There's no direct public equivalent, but several public companies compete adjacent to Klaviyo if you want transparent financials instead.
| Company | Ticker | Fit for DTC email |
|---|---|---|
| HubSpot | HUBS | Marketing automation, B2B-leaning, not DTC-focused |
| Salesforce | CRM | Marketing Cloud, enterprise pricing |
| Shopify | SHOP | Native email, simple for Shopify brands, lighter segmentation |
| Adobe | ADBE | Marketo and Campaign, too complex for sub-$10M brands |
| Intuit (Mailchimp) | INTU | Small business focus, lacks ecommerce depth |
Oracle's Eloqua and Responsys sit in the same enterprise tier as Adobe, and neither fits DTC brands under $10M either, too complex, too expensive. ActiveCampaign stays private, and Constant Contact targets solopreneurs rather than growing DTC brands.
No public company matches Klaviyo's ecommerce positioning today. Our Klaviyo vs Mailchimp platform comparison breaks down the feature gaps in more detail. If stock ownership matters more to you than fit, you're sacrificing DTC-specific features that actually drive revenue.
How to Track Klaviyo's Health Without a Ticker
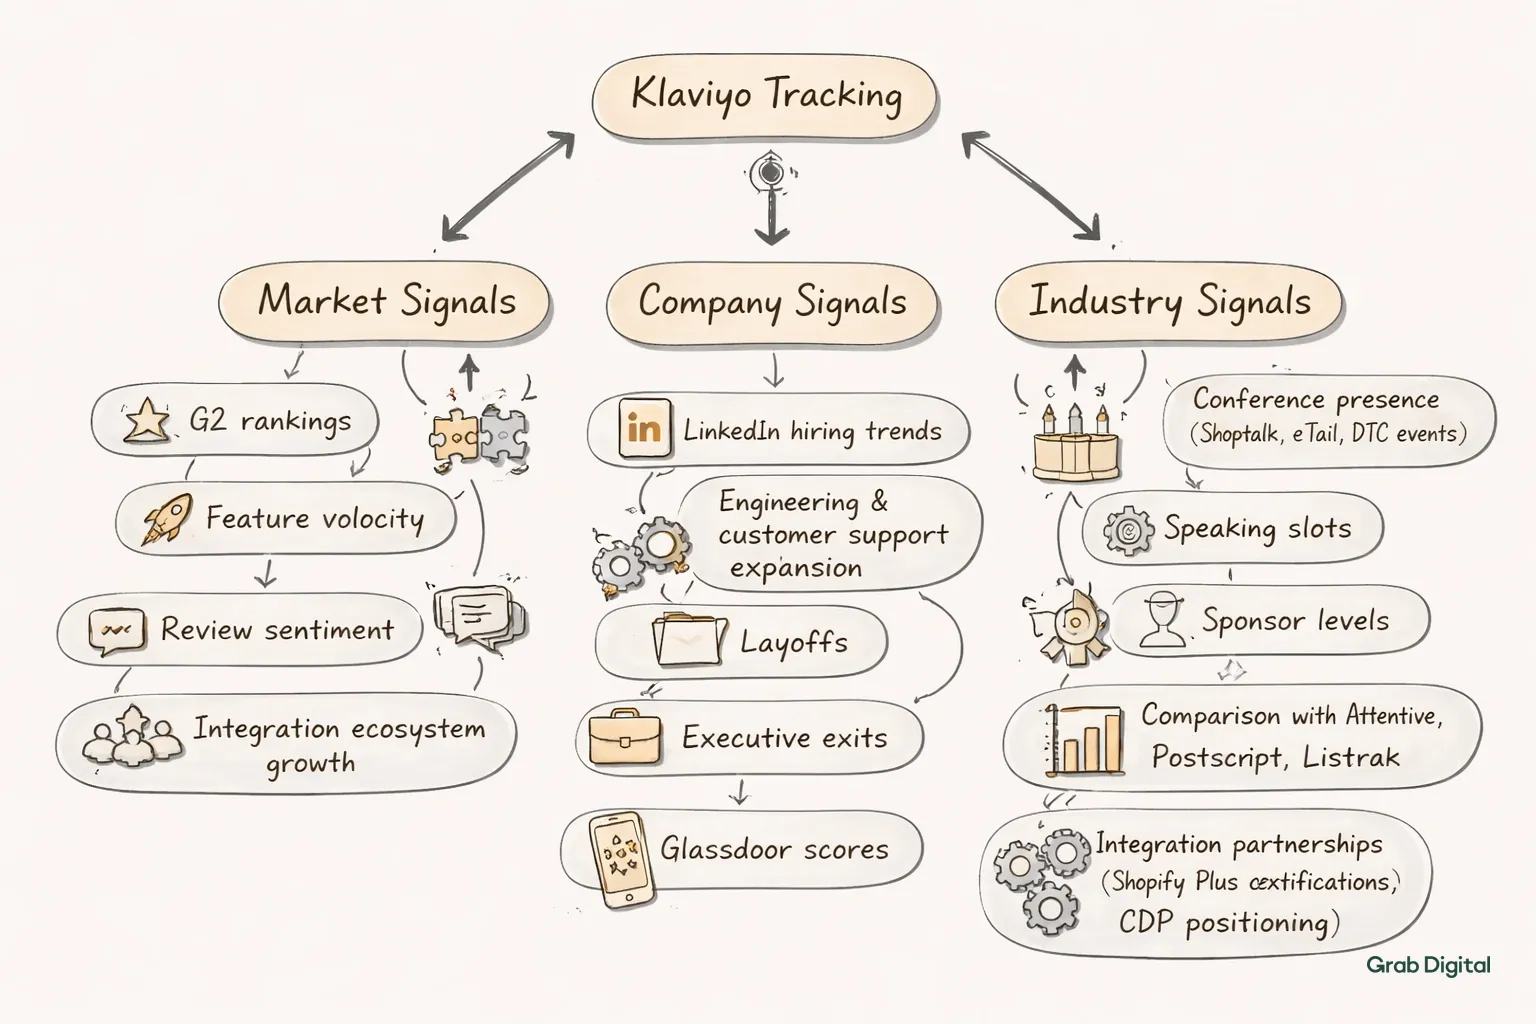
Watch product and hiring signals instead of a share price. G2 rankings, feature velocity, review sentiment, and integration ecosystem growth are better signals for a private vendor than any stock chart.
- LinkedIn hiring: engineering and CS expansion suggests growth, while layoffs or executive exits signal trouble.
- Glassdoor scores: culture trends often show up in product quality months later.
- Conference presence: showing up at Shoptalk, eTail, and DTC events, with real speaking slots, indicates market commitment. Compare that presence against Attentive, Postscript, and Listrak.
- Integration partnerships: Shopify Plus certifications, SMS expansion, and CDP positioning tend to preview where investment is going 12 to 18 months out.
For lock-in risk, these signals beat stock price every time. A thriving private company beats a struggling public one, ticker or not. The real question is whether Klaviyo keeps shipping features that solve your email revenue problems.
Will Klaviyo Go Public? IPO Odds for 2026 and Beyond
There's no credible timeline for a Klaviyo IPO as of September 2026. No refilled S-1 has surfaced, and no acquisition talk has been reported by Bloomberg or the Wall Street Journal. The safest assumption is that Klaviyo stays private through the rest of 2026.
The IPO market did improve through 2025. Rates stabilized, and SaaS valuations recovered somewhat from the 2022-2023 lows, with companies that had solid unit economics going public again. Whether Klaviyo joins them depends on strategy under CEO Andrew Bialecki, not market timing alone. Our background on Bialecki's approach covers where the company's priorities seem to be pointed.
Founders and early investors need exits eventually. Fourteen-plus years in, the cap table has investors wanting liquidity, and secondaries help but don't match IPO scale, so pressure accumulates over time.
Private equity offers another path entirely. Firms like Vista and Thoma Bravo acquire profitable SaaS companies regularly, and Salesforce or Adobe might pay a premium for Klaviyo as a strategic add-on rather than let it go public.
Market position will likely decide it. If Klaviyo maintains leadership in ecommerce email, staying independent makes sense. If it loses ground to Shopify's native tools or emerging AI-driven platforms, selling sooner starts to look better for shareholders.
How to Get Email Marketing Exposure Without Klaviyo Stock
Buy the public companies that touch the same growth, since you can't buy Klaviyo directly. Salesforce gets roughly 15% of revenue from Marketing Cloud. HubSpot gets closer to 40% from its marketing hub, with email at the core.
Shopify benefits from ecommerce growth driving email volume regardless of which tool brands actually use. More GMV correlates with more sends at scale, even if that volume runs through Klaviyo instead of Shopify's own tools.
Adobe's Experience Cloud competes with Klaviyo at the enterprise level, so strong Adobe earnings tend to signal healthy martech budgets lifting everyone in the space.
ETFs like XSW or SKYY give diversified SaaS exposure without single-stock risk. That's not pure email marketing exposure, but it means you're not betting on picking the one winner.
For DTC brands, building enterprise value in your own business beats speculative SaaS bets. Scale past $1M with good margins, optimize email attribution, and put excess cash in index funds rather than chasing a private company's paper valuation.
What Actually Matters More Than Klaviyo's Stock Status
Klaviyo stock availability doesn't touch your Q3 numbers. Whether the company is public or private matters far less than welcome series conversion, cart recovery hitting 8 to 12%, and a campaign calendar built around actual strategy.
Audit your own performance before worrying about vendor financials. Pull 90 days of Klaviyo attribution and look at email revenue as a percentage of total. Under 25% usually means execution problems that no change in ownership structure will solve.
The usual suspects are incomplete flows, weak segmentation, batch-and-blast sending, and deliverability neglect. Those alone can cost 10 to 15 points of contribution regardless of which platform you're on.
We've fixed dozens of email programs stuck at 12 to 18% attribution, and it never involves switching platforms. It takes strategy, copy, execution consistency, and watching the right metrics.
Underperforming email is an operational problem, not a vendor problem. Fix the fundamentals first, then optimize platform leverage.
Frequently Asked Questions About Klaviyo Stock
Can I buy Klaviyo stock on Robinhood or Fidelity?
No. Klaviyo is private as of September 2026, and retail brokerage accounts can't hold private equity. The only route in is through accredited-investor secondary platforms with minimums typically starting around $100,000, and that's not accessible to most retail investors.
Why did Klaviyo cancel its IPO?
Market conditions cratered SaaS valuations by roughly 40 to 60% during 2022 and 2023. Klaviyo withdrew its S-1 in late 2023 rather than accept a crushed valuation, choosing to stay private and wait for better conditions.
Is Klaviyo going public eventually?
No timeline has been announced. Klaviyo could IPO when conditions improve, take private equity money, get acquired, or stay private indefinitely. It depends on shareholder pressure and how the company's competitive position holds up.
Does Klaviyo's private status create risk for users?
Not directly. Private status gives Klaviyo flexibility without quarterly earnings pressure, but it hides financials from customers. The real risk to watch is product quality, retention, and competitive position, not the ownership structure itself.
What are Klaviyo's public competitors?
There's no direct equivalent. HubSpot (HUBS) and Salesforce (CRM) offer email marketing but target different markets. Shopify (SHOP) has native tools with lighter segmentation. Mailchimp, owned by Intuit (INTU), serves smaller accounts without Klaviyo's ecommerce depth.
Should I switch platforms because Klaviyo isn't public?
No. Platform decisions should be based on functionality, integration, pricing, and support, not stock availability. If Klaviyo is driving strong attribution for your brand, its private status shouldn't factor into that operational decision at all.
Klaviyo stock is not available to buy anywhere. As of September 2026, the company is still private after withdrawing its IPO filing in 2023, which means there's no ticker, no shares on any exchange, and no way for a regular investor to buy in.
This catches a lot of DTC brands off guard, because September 2023 had genuine IPO buzz and plenty of people assumed Klaviyo would list eventually. If you're trying to figure out whether this matters for platform evaluation or investment exposure, here's the full picture: why they pulled back, what the valuation looks like now, whether secondary markets are a real option, and what actually matters for brands running email on the platform.
Why Is There No Klaviyo Stock in 2026?
Klaviyo withdrew its S-1 filing in late 2023. The official reason was bad market conditions and strategic reasons to stay private. The translation: they didn't want to accept a crushed valuation. There is no KVYO ticker, and no listing on the NYSE or NASDAQ.
Private companies simply don't list on exchanges. You can't buy Klaviyo on Robinhood, Fidelity, or Schwab. Shareholder composition stays controlled through private funding rounds, and no open-market transactions are allowed.
That hasn't changed through September 2026. There's been no second IPO attempt. Klaviyo operates as a venture-backed private company, with ownership limited to accredited investors, institutional funds, and employees with vested options. For more on how the company's structure and roadmap tie together, our Klaviyo private company status explainer goes deeper on the specifics.
For DTC brands using Klaviyo as a platform, private status is probably good news. There's no quarterly earnings pressure forcing short-term metric chasing over customer success. If you're working with a Klaviyo agency like ours, platform continuity beats stock ticker drama every time.
What Is Klaviyo Actually Worth Right Now?
Klaviyo's last disclosed valuation was $9.5 billion, set during its 2021 Series D round. Nobody outside the company knows the current number for certain, because private valuations only update when new funding happens or secondary trades leak to the media.
Private market multiples got hit hard between 2021 and 2024. SaaS revenue multiples compressed 40 to 60 percent across the board during that stretch. Klaviyo's paper valuation almost certainly dropped from that $9.5 billion peak even without any public announcement.
Platforms like Forge Global and EquityZen occasionally facilitate private share trades for late-stage companies like this one. These deals happen between accredited investors and existing shareholders wanting liquidity. Volume is minimal, and pricing gets negotiated case by case.
There's no real secondary market for Klaviyo shares as of September 2026. Sporadic trades might happen through broker-dealer networks for high-net-worth clients, but that's not accessible to retail investors and doesn't reflect genuine market depth. Without exchange trading, price discovery stays opaque.
What Does Klaviyo's Private Status Mean for Users?
It mainly means less financial transparency, not more platform risk. Platform risk works differently for public versus private vendors. Public companies deal with regulatory scrutiny and shareholder accountability that private firms skip entirely.
Klaviyo makes product decisions without quarterly earnings calls pushing Wall Street optics over customer needs. That freedom has let them invest in CDP features, SMS expansion, and advanced segmentation without justifying burn rate to public investors. The platform has likely evolved faster without analyst expectations sitting over its shoulder.
The tradeoff is real, though: you get way less transparency. You can't pull a 10-K to check revenue growth, churn, or cash runway, so assessing long-term stability gets harder when financial health stays hidden.
For brands with real revenue flowing through email, that's worth planning around. We tell clients to diversify so no single platform controls more than 40% of attributable revenue. Even when working with a Klaviyo agency, keeping owned customer data outside Klaviyo protects your optionality if anything ever changes.
Book a free consultation to audit your email setup and find dependency risks that could hurt revenue if platform dynamics shift.
Can You Buy Klaviyo Shares on the Secondary Market?
Only if you're an accredited investor, and even then, liquidity is thin. Accredited status means a $1 million net worth excluding your primary residence, or $200,000 in annual income. That's the SEC limit on who can do private placement deals for companies like Klaviyo.
Secondary platforms match qualified buyers with existing shareholders wanting liquidity through bilateral transactions with negotiated pricing. Minimums typically start around $100,000, though real positions tend to need $500,000 or more.
Liquidity is genuinely poor compared to public markets. Public stocks trade continuously. Secondary private deals depend on matching buyer interest with seller willingness, and months can pass between lots, with spreads hitting 15 to 20 percent.
Due diligence is entirely on you in these deals. There's no analyst coverage. Projections come from company materials that aren't audit-grade, and valuation gets built from multiples applied to estimates, not audited numbers.
This works for sophisticated investors with long horizons. For retail investors wanting SaaS exposure, public options like Shopify offer actual liquidity you can act on the same day.
Should DTC Brands Care About Klaviyo's Stock Status?
Not for day-to-day decisions. The ticker doesn't change deliverability, automation, or segmentation features driving revenue right now.
But ownership does shape long-term strategy. Private companies can invest in R&D without quarterly judgment. Public companies tend to monetize users faster through price hikes and margin expansion. Klaviyo staying private potentially means more predictable pricing for mid-market DTC brands over the next few years.
Acquisition risk differs too. A private Klaviyo could get acquired by Salesforce, Adobe, or HubSpot without a shareholder vote. Public companies face proxy battles and regulatory reviews before that kind of ownership shift, which gives customers a bit more warning.
If you're a brand doing $1M to $10M, these dynamics matter less than execution. Does your email automation drive 25 to 35 percent of revenue with solid attribution? Below that, ownership structure won't fix what's actually broken.
We see brands obsessing over Klaviyo's corporate structure while their core flows stay broken and campaigns fire inconsistently. That's backwards. Build infrastructure that works regardless of vendor.
What Are the Public Alternatives to Klaviyo?
There's no direct public equivalent, but several public companies compete adjacent to Klaviyo if you want transparent financials instead.
| Company | Ticker | Fit for DTC email |
|---|---|---|
| HubSpot | HUBS | Marketing automation, B2B-leaning, not DTC-focused |
| Salesforce | CRM | Marketing Cloud, enterprise pricing |
| Shopify | SHOP | Native email, simple for Shopify brands, lighter segmentation |
| Adobe | ADBE | Marketo and Campaign, too complex for sub-$10M brands |
| Intuit (Mailchimp) | INTU | Small business focus, lacks ecommerce depth |
Oracle's Eloqua and Responsys sit in the same enterprise tier as Adobe, and neither fits DTC brands under $10M either, too complex, too expensive. ActiveCampaign stays private, and Constant Contact targets solopreneurs rather than growing DTC brands.
No public company matches Klaviyo's ecommerce positioning today. Our Klaviyo vs Mailchimp platform comparison breaks down the feature gaps in more detail. If stock ownership matters more to you than fit, you're sacrificing DTC-specific features that actually drive revenue.
How to Track Klaviyo's Health Without a Ticker
Watch product and hiring signals instead of a share price. G2 rankings, feature velocity, review sentiment, and integration ecosystem growth are better signals for a private vendor than any stock chart.
- LinkedIn hiring: engineering and CS expansion suggests growth, while layoffs or executive exits signal trouble.
- Glassdoor scores: culture trends often show up in product quality months later.
- Conference presence: showing up at Shoptalk, eTail, and DTC events, with real speaking slots, indicates market commitment. Compare that presence against Attentive, Postscript, and Listrak.
- Integration partnerships: Shopify Plus certifications, SMS expansion, and CDP positioning tend to preview where investment is going 12 to 18 months out.
For lock-in risk, these signals beat stock price every time. A thriving private company beats a struggling public one, ticker or not. The real question is whether Klaviyo keeps shipping features that solve your email revenue problems.
Will Klaviyo Go Public? IPO Odds for 2026 and Beyond
There's no credible timeline for a Klaviyo IPO as of September 2026. No refilled S-1 has surfaced, and no acquisition talk has been reported by Bloomberg or the Wall Street Journal. The safest assumption is that Klaviyo stays private through the rest of 2026.
The IPO market did improve through 2025. Rates stabilized, and SaaS valuations recovered somewhat from the 2022-2023 lows, with companies that had solid unit economics going public again. Whether Klaviyo joins them depends on strategy under CEO Andrew Bialecki, not market timing alone. Our background on Bialecki's approach covers where the company's priorities seem to be pointed.
Founders and early investors need exits eventually. Fourteen-plus years in, the cap table has investors wanting liquidity, and secondaries help but don't match IPO scale, so pressure accumulates over time.
Private equity offers another path entirely. Firms like Vista and Thoma Bravo acquire profitable SaaS companies regularly, and Salesforce or Adobe might pay a premium for Klaviyo as a strategic add-on rather than let it go public.
Market position will likely decide it. If Klaviyo maintains leadership in ecommerce email, staying independent makes sense. If it loses ground to Shopify's native tools or emerging AI-driven platforms, selling sooner starts to look better for shareholders.
How to Get Email Marketing Exposure Without Klaviyo Stock
Buy the public companies that touch the same growth, since you can't buy Klaviyo directly. Salesforce gets roughly 15% of revenue from Marketing Cloud. HubSpot gets closer to 40% from its marketing hub, with email at the core.
Shopify benefits from ecommerce growth driving email volume regardless of which tool brands actually use. More GMV correlates with more sends at scale, even if that volume runs through Klaviyo instead of Shopify's own tools.
Adobe's Experience Cloud competes with Klaviyo at the enterprise level, so strong Adobe earnings tend to signal healthy martech budgets lifting everyone in the space.
ETFs like XSW or SKYY give diversified SaaS exposure without single-stock risk. That's not pure email marketing exposure, but it means you're not betting on picking the one winner.
For DTC brands, building enterprise value in your own business beats speculative SaaS bets. Scale past $1M with good margins, optimize email attribution, and put excess cash in index funds rather than chasing a private company's paper valuation.
What Actually Matters More Than Klaviyo's Stock Status
Klaviyo stock availability doesn't touch your Q3 numbers. Whether the company is public or private matters far less than welcome series conversion, cart recovery hitting 8 to 12%, and a campaign calendar built around actual strategy.
Audit your own performance before worrying about vendor financials. Pull 90 days of Klaviyo attribution and look at email revenue as a percentage of total. Under 25% usually means execution problems that no change in ownership structure will solve.
The usual suspects are incomplete flows, weak segmentation, batch-and-blast sending, and deliverability neglect. Those alone can cost 10 to 15 points of contribution regardless of which platform you're on.
We've fixed dozens of email programs stuck at 12 to 18% attribution, and it never involves switching platforms. It takes strategy, copy, execution consistency, and watching the right metrics.
Underperforming email is an operational problem, not a vendor problem. Fix the fundamentals first, then optimize platform leverage.
Frequently Asked Questions About Klaviyo Stock
Can I buy Klaviyo stock on Robinhood or Fidelity?
No. Klaviyo is private as of September 2026, and retail brokerage accounts can't hold private equity. The only route in is through accredited-investor secondary platforms with minimums typically starting around $100,000, and that's not accessible to most retail investors.
Why did Klaviyo cancel its IPO?
Market conditions cratered SaaS valuations by roughly 40 to 60% during 2022 and 2023. Klaviyo withdrew its S-1 in late 2023 rather than accept a crushed valuation, choosing to stay private and wait for better conditions.
Is Klaviyo going public eventually?
No timeline has been announced. Klaviyo could IPO when conditions improve, take private equity money, get acquired, or stay private indefinitely. It depends on shareholder pressure and how the company's competitive position holds up.
Does Klaviyo's private status create risk for users?
Not directly. Private status gives Klaviyo flexibility without quarterly earnings pressure, but it hides financials from customers. The real risk to watch is product quality, retention, and competitive position, not the ownership structure itself.
What are Klaviyo's public competitors?
There's no direct equivalent. HubSpot (HUBS) and Salesforce (CRM) offer email marketing but target different markets. Shopify (SHOP) has native tools with lighter segmentation. Mailchimp, owned by Intuit (INTU), serves smaller accounts without Klaviyo's ecommerce depth.
Should I switch platforms because Klaviyo isn't public?
No. Platform decisions should be based on functionality, integration, pricing, and support, not stock availability. If Klaviyo is driving strong attribution for your brand, its private status shouldn't factor into that operational decision at all.

Find out exactly what your email channel is leaving on the table.

Email Marketing for Scaling DTC Brands


